On this page
Choosing the right car insurance in Dubuque means understanding more than just the price on your bill. It means knowing how your coverage actually responds when something goes wrong-whether that happens on Loras Boulevard or across the river in Wisconsin. This guide breaks down what Dubuque drivers need to know about liability, injury protection, and coverage decisions that matter for your household.

Key Takeaways
-
Iowa minimum auto insurance is 20/40/15 liability, but many Dubuque households consider higher limits because they regularly drive into Wisconsin and Illinois.
-
IowaCarInsurance.com (Drivers Insurance Agency, Inc.) is an independent agency serving Iowa drivers by phone at (844) 425-1313.
-
Liability, uninsured/underinsured motorist (UM/UIM), and medical payments coverage work together to provide injury protection-especially important when another driver has limited insurance.
-
Quotes are estimates only; actual policy terms and insurer approval control coverage.
-
Iowa drivers should regularly review their insurance policy to adapt to changing circumstances like new vehicles, added drivers, or cross-border travel patterns.
How Car Insurance Works for Dubuque, IA Drivers
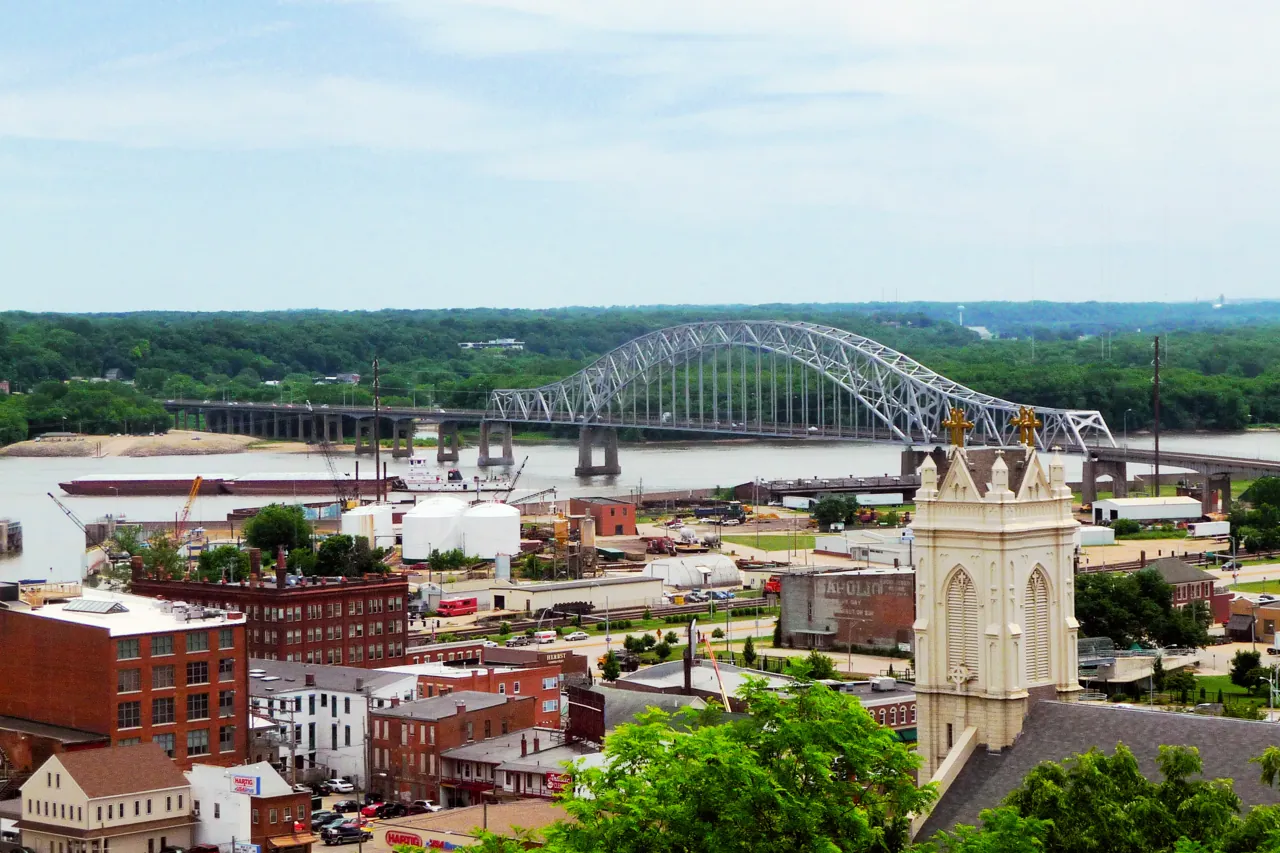
Driving in Dubuque means navigating city errands through older neighborhoods, managing hilly terrain near Clarke Drive or Grant Street, and frequently crossing into Wisconsin and Illinois along US-61/151 and US-20. These daily realities shape the kind of protection a Dubuque household needs from its auto insurance.
At its simplest, car insurance is a contract between you and an insurer. It can help pay for injuries, property damage, and certain out-of-pocket costs after a covered accident. Iowa is an at-fault (tort) state, meaning the driver found at fault is generally responsible for the other party’s injuries and property damage, typically through their liability coverage.
Start with the declarations page for selected coverages, vehicles, limits, deductibles and premium. Then read the policy forms and endorsements: declarations are a summary, not the entire contract, and not every covered situation or driver is individually listed. Ask the insurer about unclear terms.
Iowa Minimum Car Insurance Requirements (and Why Dubuque Drivers Often Buy More)
Iowa’s financial responsibility law (Iowa Code § 321A.21) sets the state’s minimum liability coverage at 20/40/15. Here is what those numbers mean:
|
Limit |
What It Covers |
|---|---|
|
$20,000 |
Bodily injury to one person per accident |
|
$40,000 |
Total bodily injury for all people per accident |
|
$15,000 |
Property damage per accident |
Iowa’s minimum liability coverage is 20/40/15, but these amounts often fall short. Consider a hypothetical two-car collision on US-20 near Dubuque where a driver causes serious injuries. If the injured person’s medical bills reach $60,000, a policy at minimum limits would leave $40,000 or more uncovered-exposure the at-fault driver would owe out of pocket. Modern vehicle repair costs can also exceed $15,000 quickly.
That is why many Dubuque drivers choose higher liability limits, such as 100/300/100. Iowa residents should verify all current insurance requirements before purchase, as laws can change. You can learn more at Iowa minimum coverage guide or call IowaCarInsurance.com at (844) 425-1313 to review policy options from multiple insurers.
Key Coverages for Dubuque Households (Liability, UM/UIM, Medical Payments & More)
Beyond the minimum, several coverage types matter for Dubuque, IA drivers who want real injury protection.
Bodily injury and property damage liability pay for injuries or damage you cause to others in a covered accident. This applies whether the accident happens in Iowa, Wisconsin, or Illinois.
Uninsured motorist (UM) coverage protects you if you are hit by an uninsured driver. Underinsured motorist (UIM) coverage helps when the at-fault driver’s limits are too low to fully cover your injuries. Together, UM/UIM coverage can be one of the most important things on your policy, especially for people who drive across state lines where the other driver’s insurance situation is unknown.
Medical payments coverage (MedPay) is optional no-fault coverage that may help pay medical or funeral expenses for covered occupants, regardless of who caused the accident. However, MedPay is not a substitute for health insurance or for reading your health plan’s deductible, copay, and exclusion terms. Households should review how their health plan and auto coverages work together.
Under Iowa Code §516A.1, UM/UIM bodily-injury coverage must be included unless the named insured signs a written rejection. Understand the protection being declined and keep any rejection with the policy records.
Other common options include:
-
Collision – covers damage to your vehicle from a crash
-
Comprehensive – comprehensive coverage protects against weather-related damages and theft; ensure policies cover local weather hazards like hail and deer collisions when insuring in Iowa
-
Rental reimbursement and roadside assistance – especially relevant for newer or financed vehicles in Dubuque
Comprehensive and collision coverage are common options that lenders typically require on financed or leased vehicles.
Crossing State Lines: Dubuque Drivers Going into Wisconsin and Illinois
Many Dubuque residents cross the Mississippi River regularly-shopping in Galena, visiting family in Platteville, or heading to medical appointments in the Tri-State area. This cross-border life raises an important question: does your Iowa auto insurance follow you?
Standard Iowa auto insurance policies generally follow the insured vehicle across state lines within the U.S. Liability coverage typically adapts to meet another state’s minimum requirements when you drive there. However, actual policy language controls what is and isn’t covered, so reading your policy matters.
UM/UIM and MedPay decisions can feel more important when traveling out of state, where you have no way of knowing whether the at-fault driver carries adequate insurance-or any insurance at all. Higher UM/UIM limits provide a broader safety net regardless of which state you are in.
Before leaving Iowa, keep these items accessible in your vehicle:
-
Current proof-of-insurance card (paper or electronic)
-
Your insurer’s claims phone number
-
Your agent or IowaCarInsurance.com contact information: (844) 425-1313
Household Example: Dubuque Family Driving in Town and into Neighboring States
This is a purely hypothetical example for illustration only. It does not predict any actual claim outcome.
Imagine a couple living near Hill Street in Dubuque with two vehicles-a newer financed SUV and an older paid-off sedan. They use the sedan for city errands and the SUV for frequent trips into Wisconsin and Illinois. Their current policy carries Iowa minimum liability (20/40/15), UM/UIM at minimum limits, no MedPay, and collision and comprehensive only on the SUV.
Suppose another driver causes a covered crash during a Wisconsin trip, and the couple’s eligible bodily-injury damages exceed the amount recoverable from that driver. Whether their own UIM responds depends on its definition, limits, offsets, exclusions and the facts. A low-limit policy does not automatically produce an additional payment.
With low UM/UIM limits: The household may have less protection for a qualifying bodily-injury claim. Do not simply add the at-fault driver’s limits to the UIM limits; policy offsets and applicable law can affect recovery.
With higher UM/UIM and MedPay: A higher UIM limit may increase protection for an eligible claim. Optional MedPay may address covered medical expenses regardless of fault, subject to its own limits and coordination provisions. Neither guarantees every bill will be paid or allows duplicate recovery of the same expense.
The contrast in financial exposure can be significant. If your household regularly crosses state lines, review your declarations page and speak with IowaCarInsurance.com about liability, UM/UIM, and MedPay choices that fit your needs.
Dubuque Driving Details: Odd/Even Snow Routes and Proof of Insurance
Local driving conditions in Dubuque create risk that goes beyond what many drivers think about when choosing coverage.
Check the City of Dubuque’s odd/even snow-route guidance, current activation notices and signs for the specific street. Restrictions and enforcement windows matter when leaving a car during snow removal. Municipal fines and enforcement towing are separate from an insured vehicle-damage claim.
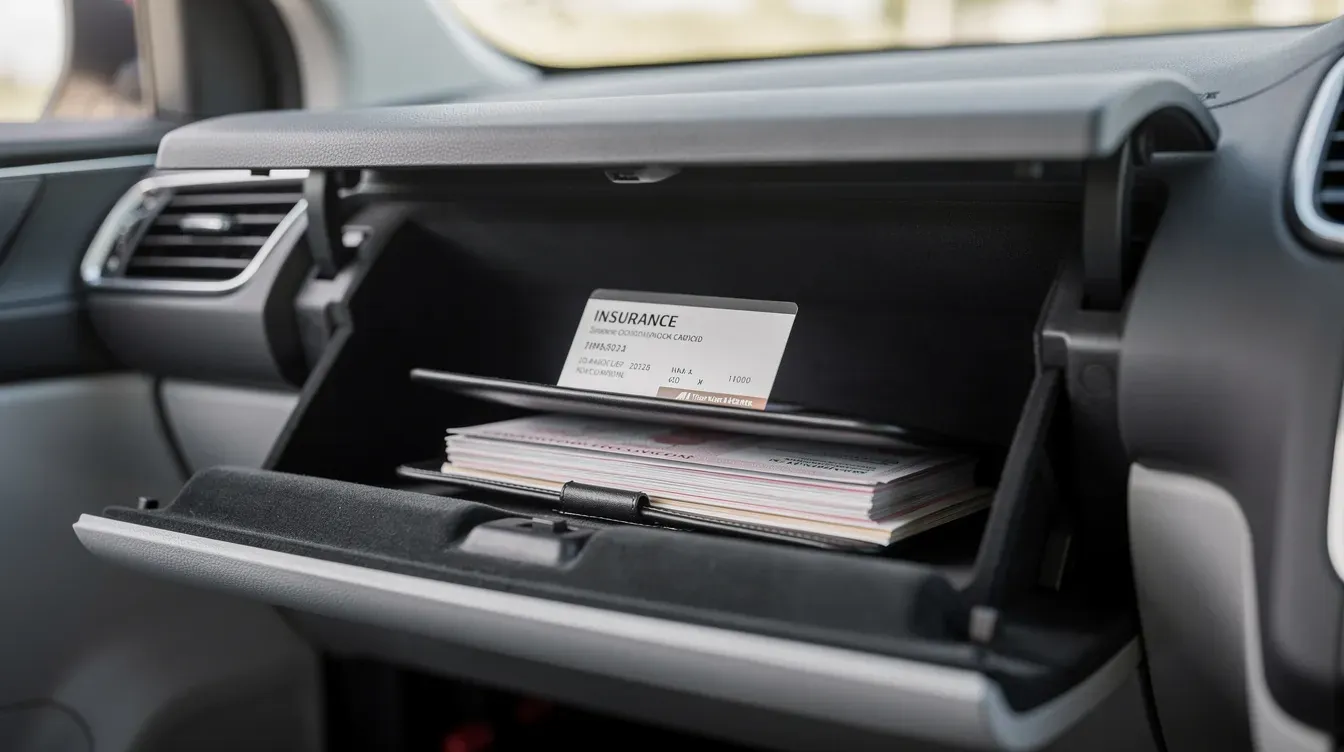
Winter also means more roadside incidents. Always keep a current proof-of-insurance card in your vehicle-Iowa regulations require it in paper or electronic form. During a winter stop or minor collision, having your proof card and insurer contact information ready can save time and stress.
Car Insurance Rates in Dubuque: What Can Affect What You Pay
Car insurance rates are set by each insurer’s filing, underwriting, and rating rules. No agency can guarantee savings, acceptance, or specific pricing. That said, understanding what influences your rate helps you make informed choices.
Common rating factors include:
-
Driving record – your driving record significantly impacts car insurance rates; accidents, tickets, and violations raise costs
-
Credit history – credit score can influence car insurance premiums in Iowa
-
Vehicle type – vehicle type can determine car insurance costs; newer, high-value vehicles generally cost more to insure
-
Garaging location – location affects car insurance rates in Dubuque, as urban and suburban areas carry different risk profiles
-
Miles driven and commuting patterns
-
Coverage selections – higher limits and lower deductibles increase premium; raising your deductible can lower your monthly car insurance payment
-
Coverage continuity – gaps in coverage often lead to higher rates
Drivers should inquire about discounts related to safe driving habits and vehicle safety features. A good student discount may apply for younger drivers in eligible households. Bundling auto insurance with home or renters insurance may yield multi-policy discounts. Drivers are encouraged to compare multiple insurance providers to find the best rates-independent agents can help compare rates across multiple insurance carriers.
A liability-only policy may cost less than full coverage (liability plus comprehensive and collision), but it leaves your vehicle’s damage unprotected after many types of losses. The best way to understand your options is to make getting a quote easy: call (844) 425-1313 and receive a quote. Remember that a quote is an estimate and does not bind coverage until the insurer issues the policy.
What to Do After an Accident in Iowa, Wisconsin, or Illinois
Every Dubuque driver should have a simple plan for what to do after an accident, whether it occurs in Iowa or across the river.
Immediate steps:
-
Ensure safety-check yourself and passengers for injuries
-
Call emergency services if anyone is hurt or the road is blocked
-
Move to a safe area when possible
-
Cooperate with law enforcement
Documentation checklist:
-
Exchange names, phone numbers, and insurance information with all involved drivers
-
Photograph damage, the scene, license plates, and road conditions
-
Note the exact location, including city and state
-
Collect witness contact details
-
Obtain the responding officer’s report number if available
Proof card and contact checklist:
-
Keep your proof-of-insurance card in the glove box or on your phone
-
Store your insurer’s claims phone number where you can find it quickly
-
Save IowaCarInsurance.com’s number-(844) 425-1313-as a contact
-
Call your insurer’s claims line as soon as reasonably possible, even when out of state
How a claim is handled depends on policy terms, fault determinations, and the laws of the state where the crash occurs. No specific claim outcome should be assumed from this article.
Working with IowaCarInsurance.com for Dubuque Auto Insurance
IowaCarInsurance.com is the Iowa-focused website of Drivers Insurance Agency, Inc., an independent insurance agency serving Dubuque and other Iowa communities by phone.
What an independent agency can offer:
-
Compare available auto insurance options from multiple companies without you having to call each one
-
Provide friendly assistance for good drivers and drivers with tickets, accidents, or coverage gaps
-
Cover liability, comprehensive, collision, Iowa SR-22 filings, non-owner insurance, and appropriate non-owner eligibility questions
Steps to get started today:
-
Call (844) 425-1313 or visit the quote page for an easy quote or review
-
Discuss your vehicles, drivers, and how you use them in Dubuque and beyond
-
Review coverage needs-including liability, UM/UIM, MedPay, and whether you need products like SR-22 filings or non-owner insurance
-
Receive one or more quotes tailored to your household
Ask for a clear explanation of available coverage, exclusions, deductibles and effective dates. The agency serves Dubuque by phone; this page does not imply a physical local office.
Quotes are proposals only, subject to underwriting. Coverage is not in force until the insurer issues a policy and the first premium is paid according to the insurer’s requirements.
Frequently Asked Questions: Dubuque Car Insurance
Does my Iowa auto insurance cover me when I drive into Wisconsin or Illinois?
Many Iowa auto policies extend liability, UM/UIM, and other coverages when driving in other U.S. states, but exact protections depend on your policy contract. Policies often adjust to meet another state’s minimum liability limits, yet your chosen higher limits still matter for larger claims. Confirm multi-state coverage and any restrictions with your insurer or by calling IowaCarInsurance.com at (844) 425-1313 before travel.
Is medical payments coverage necessary if I already have health insurance?
Medical payments coverage is optional and may help pay certain medical or funeral expenses for covered occupants after a covered accident, regardless of fault. MedPay is not a substitute for health insurance or for reviewing your health plan’s deductibles, copays, and exclusions, but it may help with some immediate out-of-pocket costs. Dubuque households should compare their health insurance features with potential MedPay options to see how the two might work together after a crash.
What happens if the other driver in a Dubuque accident has no insurance or not enough insurance?
An injured person may seek recovery from the at-fault driver directly and, depending on their own policy, from UM/UIM coverage if purchased. UM/UIM limits on your policy can become very important when the at-fault driver is uninsured or carries only low limits. Any actual claim outcome depends on the facts, policy language, and applicable state law. This information is not legal advice.
How can I find out what coverages I already have on my Dubuque car insurance policy?
Your policy’s declarations page lists each vehicle, driver, coverage type, and limit. It is usually available in print or online from your insurer. Look specifically for liability limits, UM/UIM limits, medical payments amounts, and whether comprehensive or collision are included on each vehicle. Contact your insurer or call IowaCarInsurance.com for help reading your current declarations page and discussing potential adjustments.
Can I get car insurance if I’ve had tickets, accidents, or a lapse in coverage?
Eligibility and premiums vary for drivers with tickets, accidents or gaps. If Iowa DOT requires an SR-22, its guidance describes two years from the first day of suspension or revocation; follow the individual notice and other reinstatement requirements. Non-owner eligibility also depends on vehicle ownership and regular access, not just whether a car is titled in your name. Call (844) 425-1313 to discuss available options.
Related Iowa city guides
The Davenport and Bettendorf guides offer additional examples for Iowa households that drive across the Mississippi for work. Browse the Iowa city directory for all city guides.